Nobody Ever Pays It Off. They Just Roll It Over.
A government never pays off its debt like you pay off a truck. It refinances it — forever. So the only question that matters is the rate on the new loan.
By Baron Mulberry
Sit at the kitchen table for a second and think about how a family borrows. You take a loan, you make payments, the balance goes down, and one day you own the thing free and clear. That's how normal people do debt.
Now forget all of it, because Washington has never once done it that way.
The United States owes about $40 trillion. Not one dollar of it is on a plan to be paid off. Every single loan the government has ever taken comes due on a schedule — and when it comes due, the Treasury doesn't write a check from savings. It sells a new loan that same week and uses the money to pay off the old one. Bankers call that rolling the debt over. At your kitchen table it's called refinancing — except you refinance to get a better deal. The government refinances at whatever price the market charges that week, good week or bad week. It has no choice. The bill is due.
So when people argue about “the debt,” they're mostly arguing about the wrong number. The size of the pile matters, sure. But the pile never gets paid. What gets paid — every week, without fail — is the rate on the roll. And right now the roll is repricing the whole country.
The machine nobody explains
Here's the machine, plain. Every week, some of America's old IOUs come due. The Treasury holds a sale — an auction — and sells fresh IOUs to pay off the old ones, plus fresh IOUs to cover this year's shortfall. The buyers name the price, and the price is the interest rate.
Now look at the calendar, because the calendar is the story. More than $10 trillion of the debt comes due in the next twelve months. That's about one dollar in every three the public holds — a third of the pile repricing inside a year. In the fiscal year that just ended, the Treasury refinanced $9.7 trillion of maturing loans, and about two-thirds of it was the shortest paper there is — bills, IOUs of a year or less.
Picture running a business where a third of everything you owe re-prices every single year, at whatever rate the bank feels like charging that week. That's not a metaphor for the US government. That is the US government.
Two rates: the one on the screen, and the one in the budget
Every big borrower carries two interest rates at the same time, and mixing them up is how smart people talk nonsense about this.
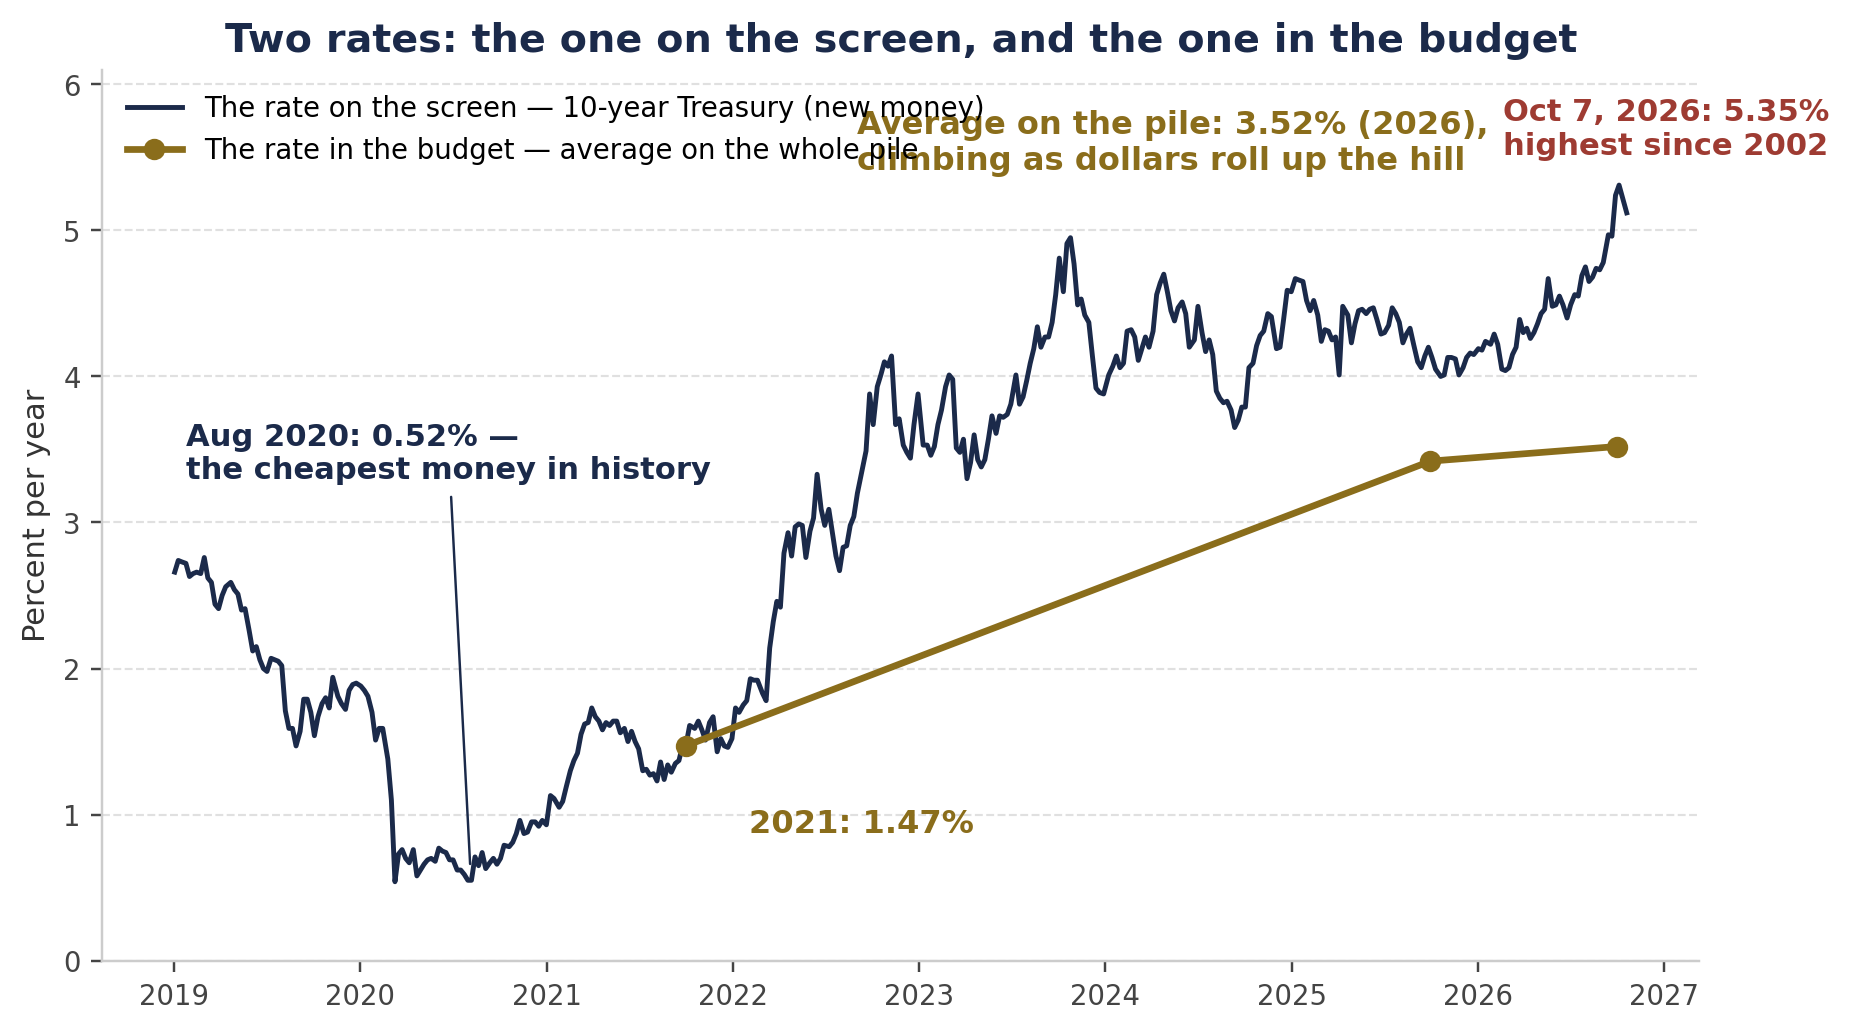
The rate on the screen is what new money costs today. On October 7, the 10-year Treasury — the benchmark loan, the one every mortgage and business loan in America keys off — touched 5.35%, the highest since 2002. When the Treasury sold $39 billion of 10-year loans the next day, buyers charged 5.3% — the highest auction price since 2000.
The rate in the budget is what the government actually pays across the whole pile — and it's only 3.52%. Why so much lower? Because most of the pile was borrowed back when money was nearly free. In 2021 the average rate on the government's marketable debt — the kind it sells to investors — was 1.47%. In August 2020, the 10-year loan itself printed 0.52% — the cheapest money in the history of the republic.
So which rate is real? Both. The budget pays 3.52% today because yesterday's loans were cheap. But a government does not pay the rate it sees on Thursday. It pays, year by year, the rates it sees on the days its debt comes due. And with a third of the pile coming due every year, Thursday's rate is walking into the budget on a schedule — roughly a third of the pile at a time, every year, until the cheap money is gone and the average has climbed the whole hill.
Nobody has to vote for this. No politician has to sign it. The calendar does it.
What the roll costs
You can watch the hill being climbed in the interest bill — the money the government pays just to rent its own debt. Not schools, not roads, not soldiers. Rent on the pile.
In the fiscal year that ended September 30, net interest cost $1.05 trillion. That's about $2.9 billion a day. It is now the third-biggest line in the federal budget, ahead of the entire military, for the third year running. As a share of the whole economy it hit 3.2% — past the previous record, set in 1991. More than one tax dollar in five now goes straight to interest.
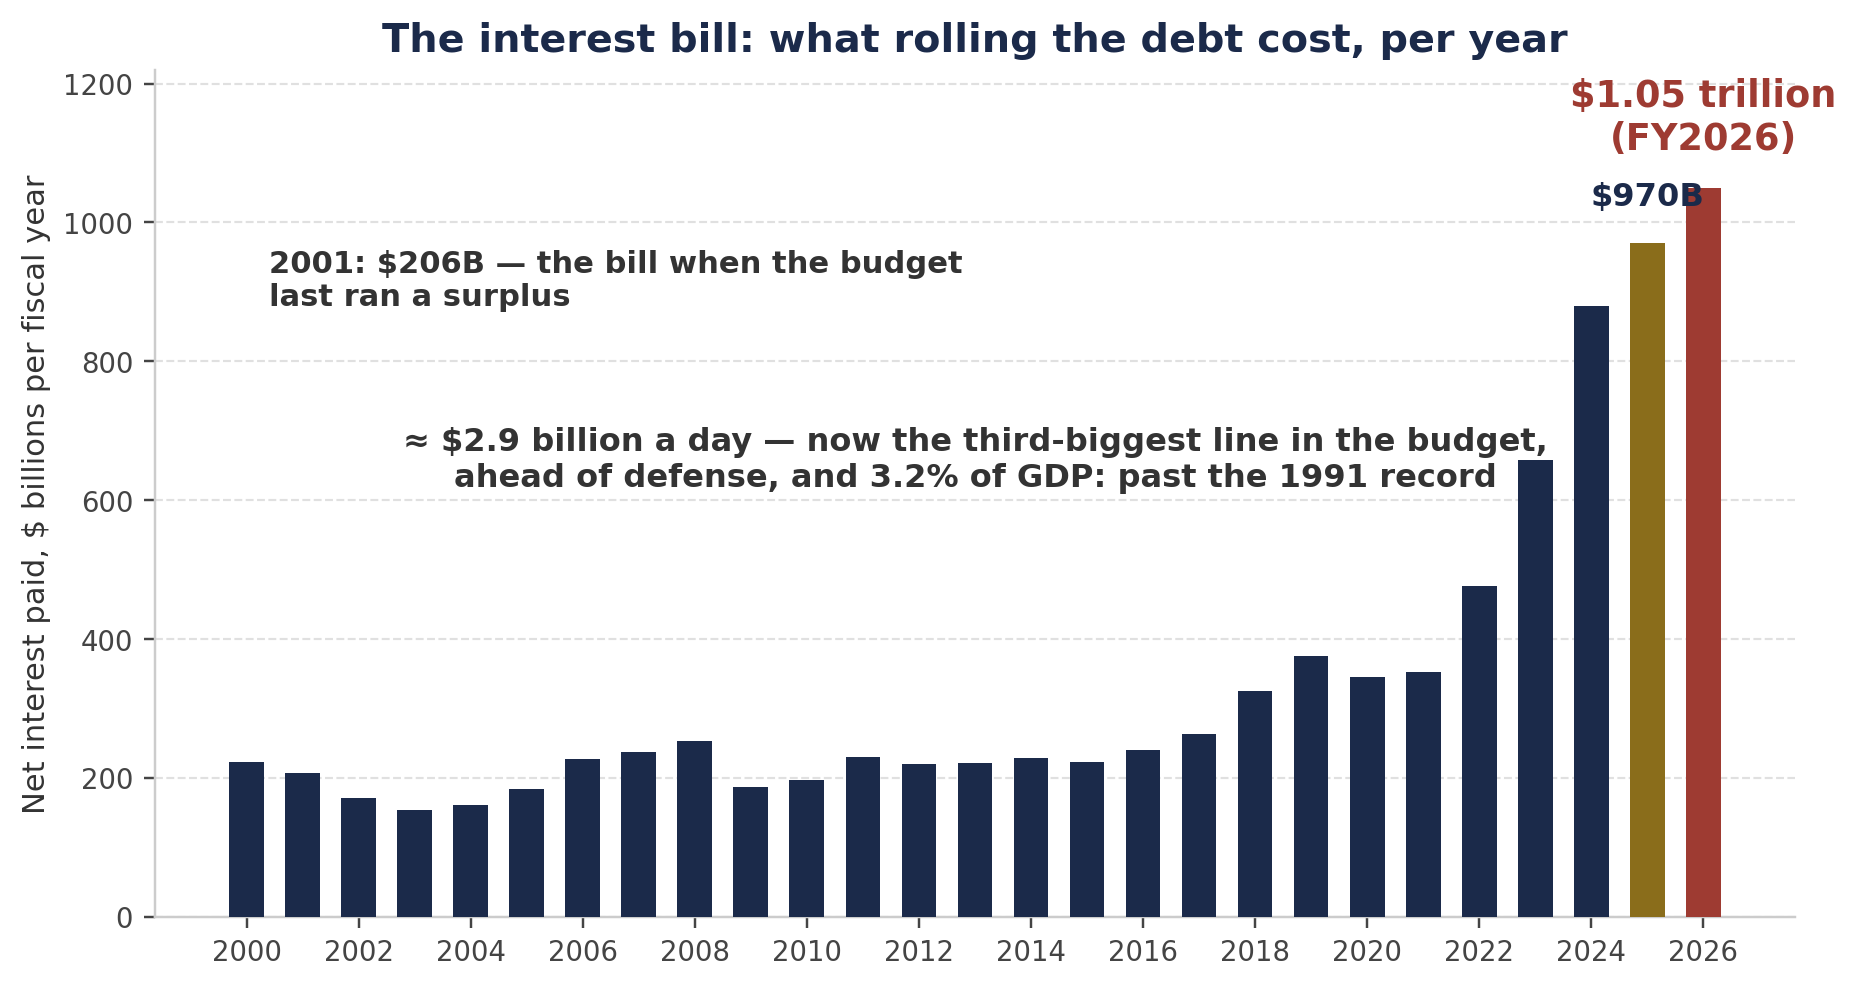
In 2001 — the last time the budget ran a surplus — the interest bill was $206 billion. The pile was smaller, money was dearer, and the bill was still a fifth of today's. Nobody passed a law that said “let's spend a trillion a year on interest.” The rollover passed it, one refinancing at a time, while everyone was watching something else.
And here's the part that should bother anybody who plans anything: the government's own map is already wrong. The Congressional Budget Office — the official scorekeepers — built this year's outlook on the 10-year loan costing 4.1%. It costs 5.3%. Every projection, every “the debt stabilizes at such-and-such” chart you have ever been shown was drawn with cheap money in the pen. The roll doesn't care about the map.
George's question
My best friend George argues the other side of this with me most mornings — the market will muddle through, the US has advantages, control what you can control. This week he said the quiet part out loud, and it's the only question that matters:
“Debt and deficits are the highest on record while the economy is growing — so what happens when there's another recession?”
Sit with that. The fiscal year just closed with a $1.99 trillion deficit — $5.4 trillion came in, $7.4 trillion went out — in a good year. Full employment, growing economy, record tax receipts, and the government still spent two trillion it didn't have. In a bad year, the receipts fall, the spending jumps on its own — unemployment checks, bailouts, the whole automatic machinery — and the gap gets dug at 5% money, with a third of the pile repricing into the hole.
George also had the line for how we got here: “Penny wise, dollar foolish.” In 2020 and 2021, the Treasury could have locked in 30-year money at under 1% — the mortgage deal of the century, stretching the nation's loans out long at the lowest rates ever printed. Instead, under both parties, it kept borrowing short because short was a hair cheaper that quarter. Any homeowner who ever passed on locking the low rate — and then watched it double — knows exactly how this story ends. It ends with the roll.
France is the same machine, a few exits further down the road
If you want to see where the roll ends when a country loses the room to muddle through, look at France — same machine, further down the road, and graded today.
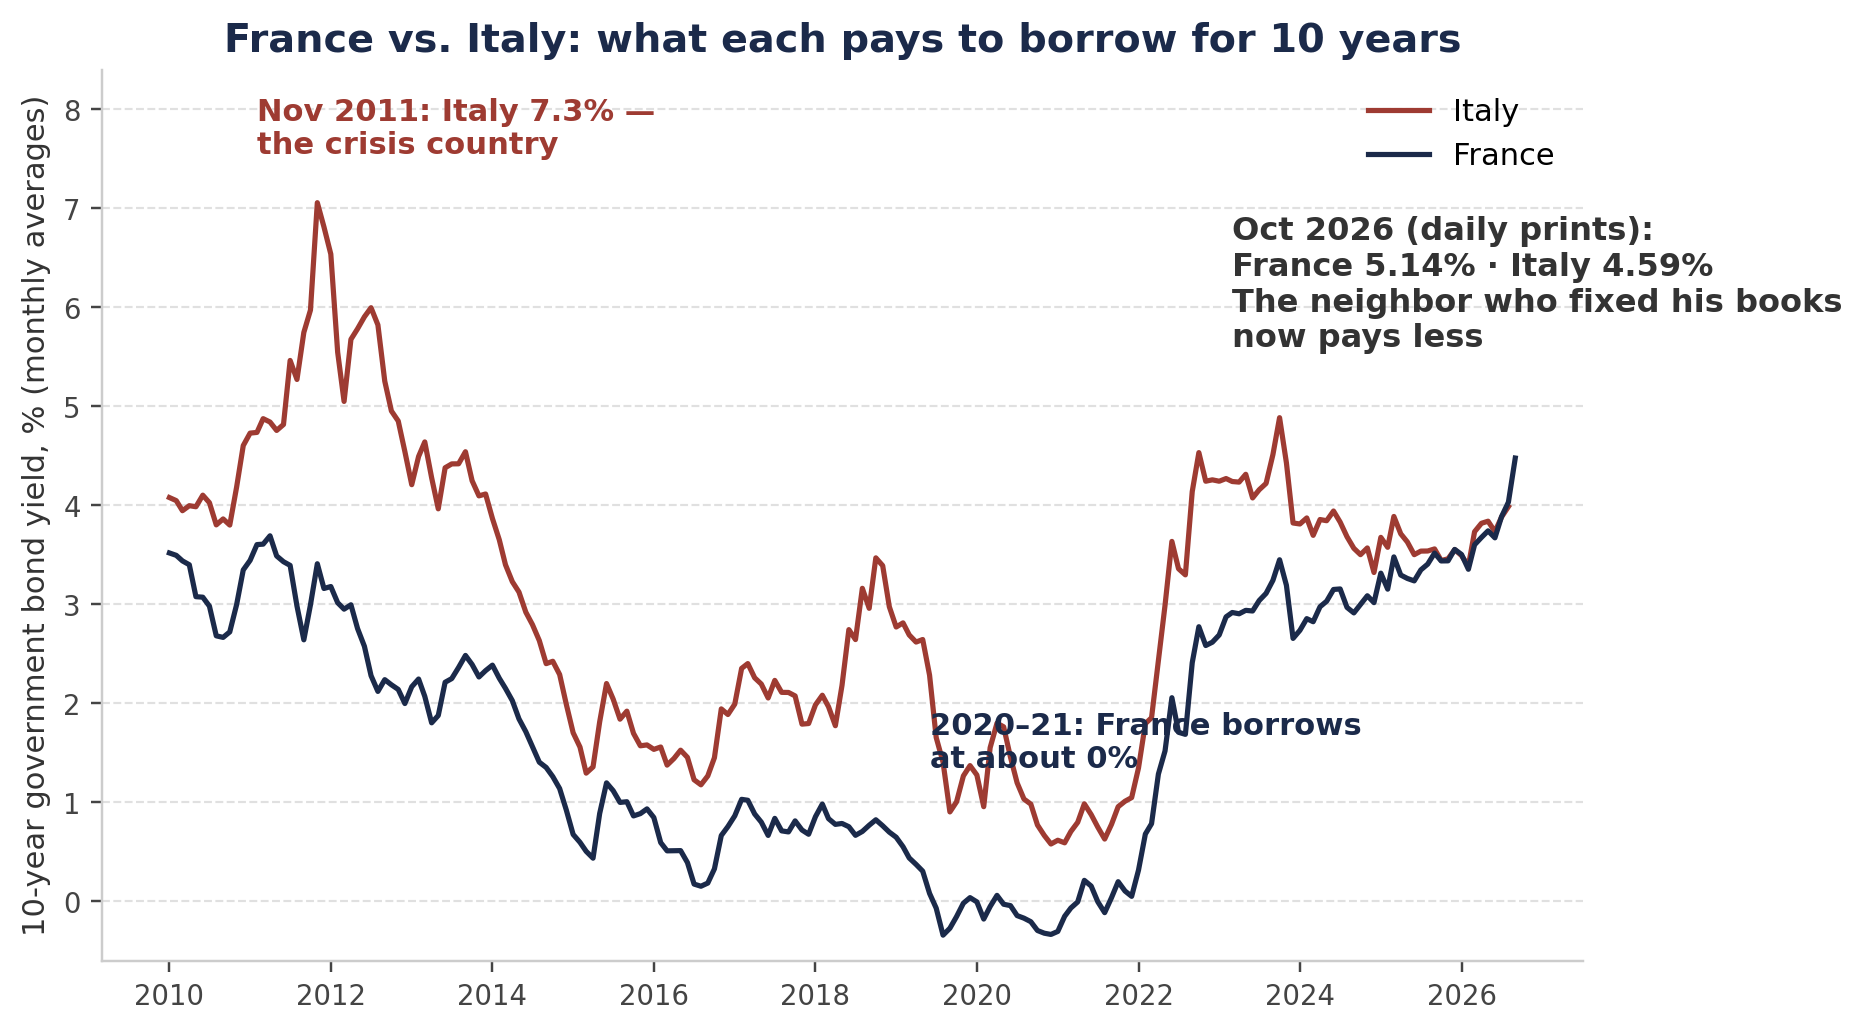
France owes 119% of its GDP — the whole pile measured against everything the country produces in a year — and runs one of Europe's biggest deficits. This week its 10-year loan printed 5.14% — the highest since 2002. France now pays more to borrow than Italy.
Read that again, because fifteen years ago it was unthinkable. Italy was the crisis country — 7.3% in 2011, the cautionary tale, the place that was going to blow up the euro. Italy spent the years since quietly fixing its books. France kept partying. Today the market charges the party 5.14% and the neighbor who did his homework 4.59%.
It's not about the protests in the streets, however loud they get. It's about the books. Two of the three big grading agencies have already cut France's credit rating. The third, Moody's, hands down its verdict today, after US markets close — and the analysts' shrug tells you everything: a downgrade is “already priced in.” Of course it is. The price moved first. The grader is just catching up to what the roll already charged.
That's the sequence, everywhere it happens: the rate moves, the average climbs, the interest bill eats the budget, and the graders arrive last with their stamps. By the time it's official, you've been paying it for years.
UPDATE — Moody's verdict, October 23, 2026:
Moody's kept France at Aa3 and left its warning label on (a negative outlook — the next move is still more likely down than up), sparing the downgrade most analysts expected, on the assumption that a deficit-cutting 2027 budget actually passes. The market's verdict didn't wait and didn't change: France pays 5.14% to borrow, more than Italy — grader or no grader, the roll charges what it charges.
The operator's page
So what does a mom-and-pop do with a machine this size? You can't set the rate. Neither can I. What you can set is your own roll — and that's the whole game.
One: when money is cheap, lock it long. The Treasury didn't, and it will pay for that miss every week for a generation. Your version is smaller and you control it completely: never let everything you owe come due in the same bad season. Spread your maturities like you spread your work.
Two: kill the expensive debt first, while the timing is yours. Debt you retire on your schedule never gets rolled on the bank's. Every dollar of high-rate debt you kill is a dollar that can't reprice against you in a bad year.
Three: keep a war chest the freeze can't reach. Cash reserves — ours sit in cash-value storage, the Infinite Banking way — exist for exactly one reason: so a roll, a rate spike, or a bad quarter never forces you to sell something good at a bad price. The government rolls because it has no reserves. A household rolls because it didn't build any. The machine runs either way. The only question is whether it runs over you.
“Debt does not get paid down. It gets rolled over. They can only lower the speed.”
That's true for France, true for Washington — and it's true at the kitchen table, where at least you get to choose your speed yourself.
Roll your own book before the market rolls it for you.
Sources
US Treasury final fiscal 2026 figures (year ended Sep 30, 2026): deficit $1.99 trillion; revenue $5.4 trillion; outlays $7.4 trillion; net interest $1.05 trillion; gross interest $1.36 trillion; average interest rate for the year 3.53%. Treasury Fiscal Data and Joint Economic Committee debt update: average rate on marketable Treasury debt 3.52% at end-September 2026, vs 1.47% five years earlier; about 33% of marketable debt matures within 12 months; more than $10 trillion matures over the next 12 months. Government Accountability Office: Treasury refinanced $9.7 trillion of maturing securities in fiscal 2026, about two-thirds of it Treasury bills. Peter G. Peterson Foundation: net interest equaled 3.2% of GDP in fiscal 2026, surpassing the prior record set in 1991; interest is the third-largest federal outlay, ahead of national defense for a third straight year. CNBC: the 10-year Treasury yield touched 5.35% on Oct 7, 2026, its highest since 2002; the $39 billion 10-year note auction cleared at 5.30%, the highest auction yield since 2000; the Congressional Budget Office's February baseline assumed a 4.1% average 10-year yield for 2026. FRED (Federal Reserve Bank of St. Louis): gross federal debt (GFDEBTN) $39.5 trillion at Q2 2026 — the $40 trillion mark was crossed in September 2026; net interest by fiscal year (FYOINT), including $970 billion in fiscal 2025 and $206 billion in fiscal 2001; daily 10-year yield (DGS10), low 0.52% in August 2020; France and Italy 10-year yields (IRLTLT01FRM156N, IRLTLT01ITM156N). INSEE (Sep 29, 2026): French public debt €3,595.5 billion, 119.0% of GDP. Reuters and Dow Jones (Oct 22–23, 2026): France's 10-year yield reached 5.14%, its highest since July 2002, with the spread over German bunds at a 15-year high; Italy's 10-year yielded 4.589% on Oct 22; S&P and Fitch cut France earlier; Moody's review of France (Aa3, negative outlook) was due after 2000 GMT on Oct 23, 2026 — after this piece was written — with most analysts expecting a one-notch cut. Quoted lines are from the author's own message thread with George, Oct 22–23, 2026.
Baron Mulberry writes as BlueCollarQuant — blue-collar operator, quant thinking. Real assets, real cycles, no fluff.